State Estimation (ECE 4/5973)

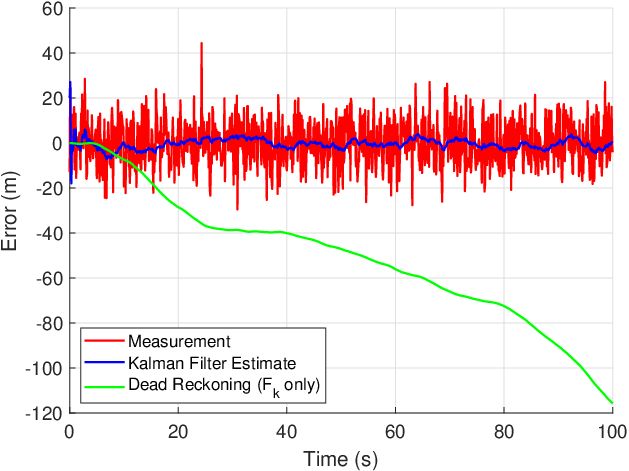

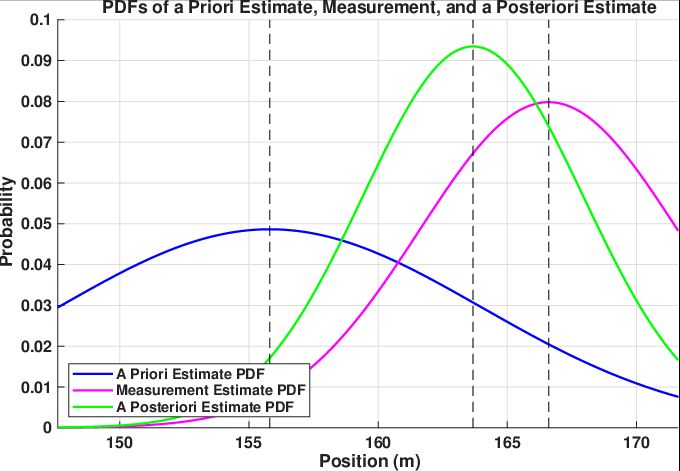
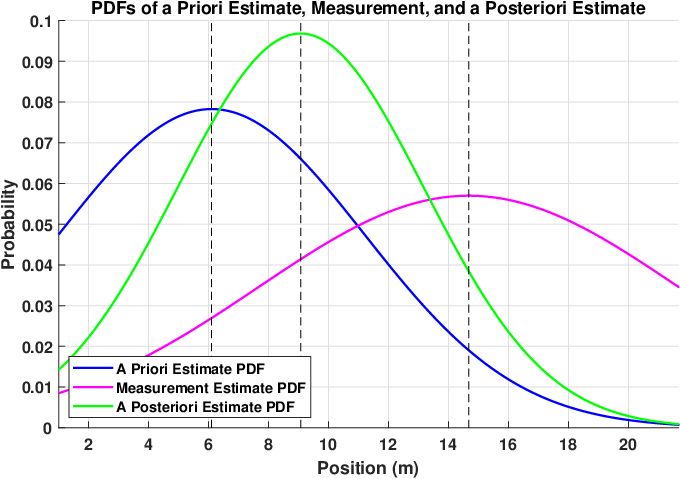

This course focuses on the mathematics and implementation of time-series state estimation algorithms, with an emphasis on various versions of the Kalman filter. The course covers mathematical preliminaries including the theory of linear systems, probability theory, and least-squares estimation, followed by the linear discrete-time Kalman filter and many practical extensions of the Kalman filter for different use cases. Time-permitting, the course will also introduce the filter. Because many practical engineering problems involve nonlinear dynamics such as navigation and radar target tracking, among others, the course will also present nonlinear filtering approaches including the extended Kalman filter, the unscented Kalman filter, and the particle filter as time allows. Emphasis will be placed on project-based learning, primarily in MATLAB, to provide a close tie between theory and practice.
Semesters Taught
- Fall 2025
- Fall 2026